

Rain Instant Pay
by Rain Technologies Inc
4.7
- Safety
- 100% Safe
- Category
- Business
- Ratings
- 4.7
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
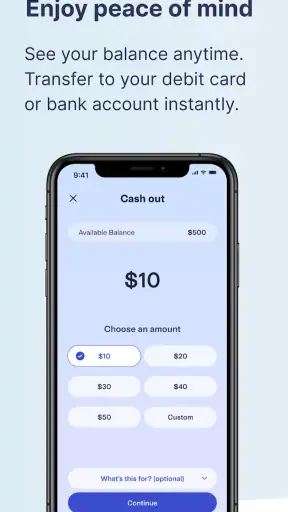
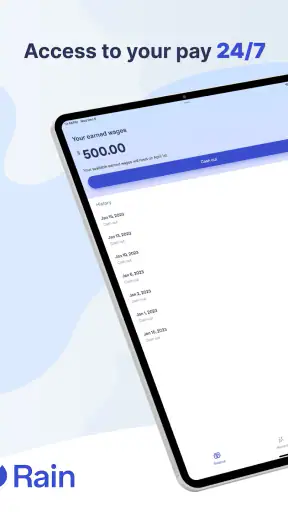
 Analysis by Getfullapps
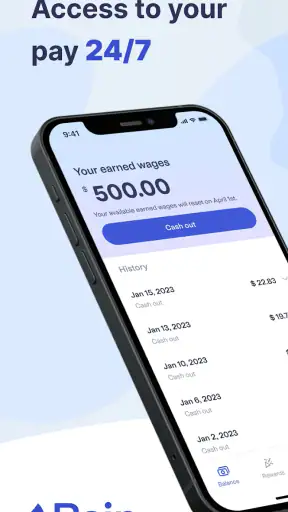
Rain Instant Pay is a business app built around one practical idea: giving employees access to their employer benefits through a mobile experience. I see it as a tool for managing the timing of earned pay rather than as a full replacement for a bank account, budgeting app, or payroll system. That distinction matters, because the value is strongest when a small timing problem is causing real stress.
In my experience, the app makes the most sense for someone who has already earned money but needs to handle an expense before the normal payday arrives. A forgotten bill, an urgent trip, or a grocery run near the end of a pay cycle can make a regular schedule feel surprisingly restrictive. Rain Instant Pay is aimed at that gap. Its store summary is brief, but the product’s identity is clear: it connects an employee with benefits made available through the employer.
The app is free to install and is rated for Everyone, which makes it approachable for a broad working audience. Rain Technologies Inc is the developer, and the app has built a sizeable user base, with over 500 thousand installs and a 4.7 average from around 34 thousand ratings. Those figures suggest that the central idea is easy for many people to understand, although they do not remove the need to check whether the benefit is actually available through your own workplace.
Rain Instant Pay in everyday use
I find Rain Instant Pay easiest to judge by looking at the moments when the connection matters: linking the workplace benefit, checking what is available, and deciding whether early access fits the next pay cycle. I would treat a reliable connection as part of the task, not just a convenience, and avoid making a rushed money decision while distracted. That perspective also helps clarify where the app fits into a busy day.
The useful capability is timing, not extra income
The most important thing to understand is that instant pay does not create additional earnings. It changes when eligible pay can be accessed through an employer benefit. That makes the app potentially helpful, but it also means I would use it with a clear purpose rather than treating it as a permanent income boost.
That difference is easy to overlook when money is tight. If I use an early-pay option to cover a bill today, the next regular paycheck may feel smaller because part of the earned amount has already been made available. The immediate problem is solved, but the following pay cycle still needs planning. I would therefore think of Rain as a short-term cash-flow tool, not a way to stretch a salary indefinitely.
This is where the app’s business category is relevant. It is tied to an employment benefit, so it belongs alongside payroll and workplace tools rather than alongside ordinary money-transfer apps. A typical payment wallet may help me send or receive funds, while a budgeting app may help me plan spending. Rain Instant Pay addresses a different moment: the space between work already completed and the standard payday.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What the setup means for a new user
The first question I would answer before installing it is whether my employer participates in the Rain benefit. The app is designed to unlock employer benefits, so downloading it alone is not the same as becoming eligible. This is an important practical filter for anyone comparing it with a normal bank account or a general-purpose cash advance service.
Once the workplace connection is relevant, the app becomes more useful as a dedicated access point than as a broad financial dashboard. I would keep my employer and payroll details ready, read each screen carefully, and avoid rushing through any confirmation step. A benefit connected to employment deserves the same attention I would give to a payroll change, especially when the timing of later income is involved.
The current version is 2.7.1, and the app was released on February 1, 2020. I mention that because Rain is not a brand-new experiment with an untested concept; it has had time to establish its place as a workplace-focused product. At the same time, version numbers and age do not tell me whether every employer setup feels identical, so I would judge the experience partly by how clearly my own workplace connection is handled.
A realistic end-of-cycle example
Imagine I am paid on a regular schedule and my car needs an unexpected repair a few days before payday. Waiting may mean missing work, but putting the repair on a high-cost credit option could create a longer problem. If my employer makes the Rain benefit available and I have eligible earnings, the app may give me a way to address the immediate gap.
The sensible workflow would be to use only what solves that specific problem, then update my spending plan for the next payday. I would not use the available amount simply because the app shows that access is possible. The strongest benefit comes from matching the withdrawal to a known need, not from turning early access into casual spending money.
That example also shows why the app is not equally useful for everyone. Someone with a stable emergency fund may prefer to keep using savings and avoid changing the timing of pay. Someone who regularly reaches the end of every pay cycle without enough money may need a broader solution, such as revising fixed expenses, changing bill dates, or speaking with a financial counselor. Rain can help with timing, but it cannot repair an income-and-expenses mismatch by itself.
How it compares with familiar alternatives
Compared with a traditional bank overdraft, an employer-linked pay benefit may feel more connected to money I have already earned rather than money I have not yet received. That can make the purpose easier to understand. However, a bank account remains more versatile for everyday banking, saving, direct deposits, and long-term money management.
Compared with a credit card, Rain Instant Pay is not primarily about borrowing against a credit limit and carrying a balance. That may be attractive to someone trying to avoid adding another revolving account to their finances. The trade-off is that its usefulness depends on employment eligibility and the way the benefit fits into the user’s payroll arrangement.
Compared with a budgeting app, Rain offers less value for forecasting spending unless I use it alongside a separate budget. A budget can show me why I am short and help me plan months ahead; Rain is more focused on the immediate access question. I would pair the two if cash-flow timing was a recurring concern, rather than expecting one app to handle both jobs.
Compared with asking an employer for a payroll advance, the app may provide a more self-service route when the workplace benefit is active. Still, a direct conversation with payroll may be better when the issue involves a correction, a missing payment, or a question about employment records. An app should not replace a human payroll contact when the underlying pay information is wrong.
The trade-off behind convenience
The convenience is also the main risk. Easy access can make an urgent decision feel harmless, even though it changes the shape of the next paycheck. I would treat every use as a transfer of timing, not as a discount or bonus. Before confirming, I would ask myself whether the expense is necessary, whether the next pay cycle can absorb the change, and whether another option would cost less or create less disruption.
I would also avoid assuming that the app is the right answer for recurring bills. If rent, utilities, or food costs repeatedly arrive before pay, using early access every cycle could hide a structural problem. In that situation, the more useful action may be negotiating due dates, building a small buffer, or reviewing subscriptions and fixed commitments.
Another trade-off is dependence on the employer relationship. A general savings account remains useful even after changing jobs, while an employer benefit is naturally connected to work. That does not make Rain a poor choice; it simply means I would not build my entire financial system around it. I would keep ordinary banking and budgeting arrangements separate.
Who is likely to gain the most
Rain Instant Pay is most appealing to an employee who has predictable earnings, an active employer benefit, and an occasional need to bridge a short gap. For that person, the app can turn a stressful wait into a manageable timing decision. It may also suit someone who wants a workplace-linked option instead of relying immediately on a credit card or overdraft.
I would be more cautious if my hours change substantially from week to week, if my pay records are often corrected, or if I already struggle to cover essential costs from one payday to the next. In those situations, early access may offer relief today while making the next cycle harder. The app should support a plan, not substitute for one.
It is also not the best fit for someone looking for investment tools, detailed expense categorization, credit-building features, or a complete banking replacement. The product’s strength is narrower and more practical. I appreciate that focus, because a tool designed around one financial moment can be easier to use than an overcrowded money app, but the narrow focus also sets clear limits.
Small habits that make the feature safer
My first tip would be to decide the purpose before opening the app. “I need to cover the repair” is a safer starting point than “I want to see how much is available.” The second is to check the next payday budget immediately after using the benefit, while the reason for the transaction is still clear.
I would also keep a simple record of each use in the same place where I track bills. That makes it harder to forget that the next paycheck has already been partly allocated. If the app becomes necessary more than occasionally, I would treat that pattern as useful information and investigate the underlying expenses instead of increasing reliance on early access.
A final practical habit is to separate urgent needs from convenience purchases. A necessary prescription, transport cost, or work-related expense has a different priority from an impulse purchase. Rain Instant Pay can make both feel equally accessible, so the judgment has to come from me. The app provides the opportunity; it does not decide whether the expense is wise.
My overall view after looking at its role
I like Rain Instant Pay because its central purpose is easy to grasp: it gives eligible employees a way to use an employer benefit when payday timing is the problem. The free price and Everyone age rating make it easy to try, and the strong average rating from thousands of users indicates that many people find the concept worthwhile. Its 4.2 thousand reviews also show a substantial amount of user feedback around the experience.
Still, I would recommend it with one condition: use it deliberately. It is not free money, a replacement for savings, or a universal answer to financial pressure. Its best use is a controlled bridge for an occasional, necessary expense when the earnings are already connected to the workplace benefit.
For an eligible employee who understands that trade-off, Rain Instant Pay can be a genuinely practical addition to a financial routine. I would install it when I needed employer-linked access and wanted a focused tool rather than a full banking platform. If I needed long-term budgeting, savings growth, or a solution to consistently insufficient income, I would choose a different primary tool and keep Rain in a supporting role.
My recommendation: use Rain Instant Pay as a careful cash-flow bridge, not as a habit. That mindset captures both its real strength and its most important limitation. When the problem is simply waiting for payday, it can be useful. When the problem is that the numbers never work, only a broader financial plan will solve it.
Pros
- Fast access to earned wages without waiting for payday.
- Simple interface makes requesting payments easy for most users.
- Can help manage cash flow between regular paychecks.
- Useful for handling unexpected expenses or urgent bills.
- Payment history can make received advances easier to track.
Cons
- Availability may depend on employer participation and eligibility rules.
- Early wage access can include fees for certain transfer options.
- Frequent advances may make budgeting for payday more difficult.
- Identity and employment verification require sharing personal information.
- Support and transfer times may vary by bank, region, or payment method.
FAQs for Rain Instant Pay
What is Rain Instant Pay and how does it work?
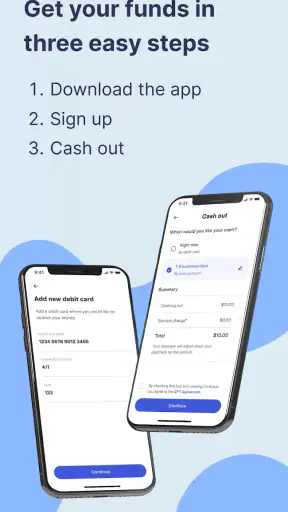
Rain Instant Pay is a financial service designed to give eligible employees faster access to part of their earned wages before the regular payday. After creating an account and completing the required verification, users may be able to view available earnings and request an instant or expedited transfer. Availability, limits, and processing times can depend on the employer, payroll data, account status, and the selected delivery method.
Is Rain Instant Pay available to everyone?
No. Access to Rain Instant Pay generally depends on whether your employer participates in the service and whether your employment and payroll information can be verified. Even when an employer is supported, individual eligibility may vary based on payroll records, work history, earned wages, account verification, and other requirements. If the app does not recognize your employer, you may not be able to use its wage-access features.
How quickly can I receive money through Rain Instant Pay?
The time required to receive funds depends on the transfer option you choose and the financial institution receiving the payment. Some delivery methods may provide funds quickly, while standard bank transfers can take longer, especially outside business hours, on weekends, or during holidays. The app should display the applicable timing and any fee before you confirm a withdrawal.
Does Rain Instant Pay charge fees for accessing wages?
Rain Instant Pay may offer different transfer methods, and some options can involve fees while others may be slower or subject to different conditions. Charges can also vary according to your employer arrangement, location, account type, and the destination account or card. Before requesting money, carefully review the confirmation screen so you understand the total cost and amount you will receive.
Is Rain Instant Pay safe to use, and what information is required?
Rain Instant Pay may require personal, employment, banking, or identity information to verify your account and connect the service with payroll records. Users should download the app only from an official store, use a strong unique password, and review permissions and privacy disclosures. Avoid sharing login codes with anyone, and contact official support if you notice suspicious activity or an unexpected transaction.

Rain Instant Pay
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via care@rain.us, visit http://rainapp.com, or review their https://www.rainapp.com/terms/privacy-notice.










